How Much House Can I Afford vs. How Much House Should I Buy?
Your maximum mortgage approval and your ideal home-buying budget are not always the same. Learn how to choose a payment that fits your goals.
 Jason Herbert 4 min read
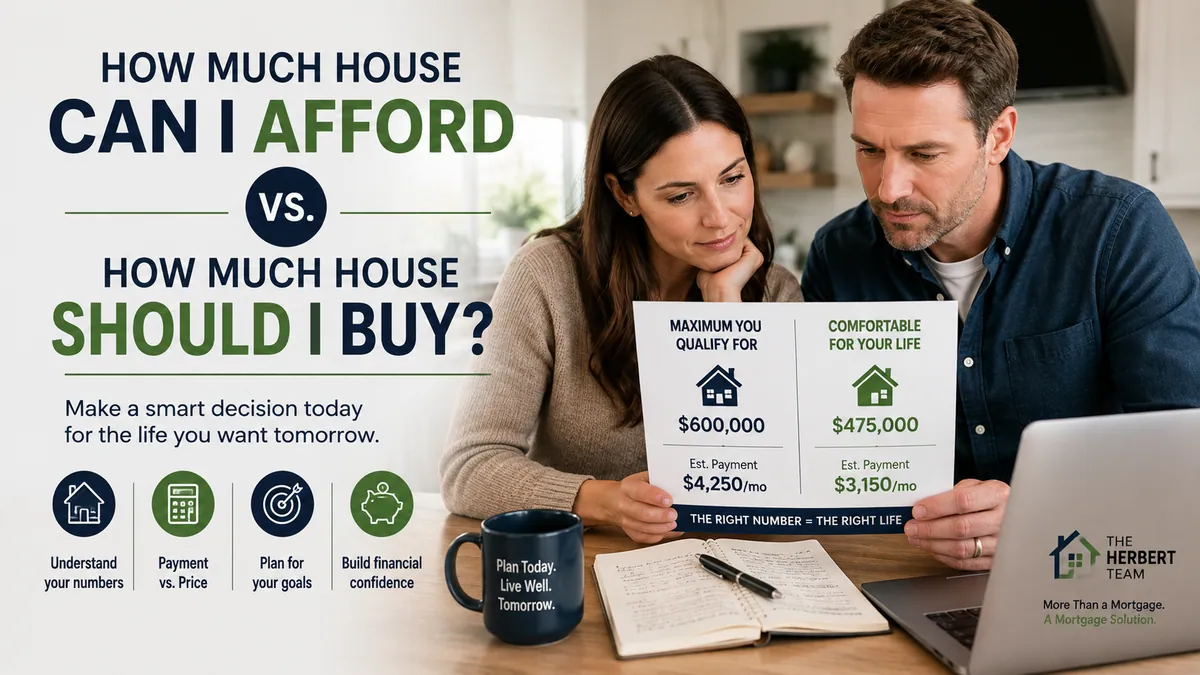
Almost every buyer asks me some version of the same question:
“How much house can I afford?”
That is an important question. It is also incomplete.
The more useful question — the one that keeps people out of payment stress later — is this:
“How much house should I buy?”
Those two numbers are not always the same. Understanding the difference is one of the most valuable conversations you can have before you tour a single home.
What “how much can I afford” usually means
When most people say afford, they mean the maximum a lender will approve.
Underwriting looks at income, debts, credit, down payment, and program guidelines, then produces a top-line number. That number is a regulatory and investor maximum — not a lifestyle recommendation.
It does not know:
- That you want to keep maxing out retirement contributions
- That daycare or private school is already a big monthly line item
- That you travel for work, support family, or carry uneven self-employed cash flow
- That you plan to buy furniture, build a fence, or replace an HVAC system in year one
The approval answers, “What is the most a guidelines engine will allow?”
It does not answer, “What payment still lets you live the life you want?”
What “how much should I buy” actually means
Should starts with your real monthly life and works backward.
I ask buyers:
- What payment still feels comfortable after taxes, insurance, and HOA in Texas?
- What do you want left over for savings, travel, kids, and the unexpected?
- How long do you plan to stay in this home?
- Are you stretching for the house — or stretching for the payment?
Then we reverse-engineer a purchase price from a payment you can live with, not the highest letter a computer will print.
In practice, that comfortable number often lands 10% to 15% below the maximum approval. Nobody has ever called me a year later to complain that their payment was too easy to carry.
Why buying at the maximum gets people in trouble
Buying at the ceiling works on paper. Life does not stay on paper.
A rate that looked fine at lock can feel different after insurance renews. Texas property taxes are a real monthly cost, not a footnote. A new car, a medical bill, or a slower business quarter can turn an “approved” payment into a stressful one.
There is also an emotional trap: once you tour homes at the maximum, everything below it feels like a downgrade — even when the lower payment is the smarter long-term move.
Approval is capacity. Budget is strategy.
Capacity gets you into a house. Strategy is what keeps you glad you bought it.
How do I choose the right number?
Here is the process I walk buyers through:
1. Start with the payment, not the price
Pick a monthly housing payment that still leaves room for the rest of your life. Include principal, interest, taxes, insurance, and HOA if applicable.
2. Build the payment with real Texas numbers
National calculators often underestimate Central Texas taxes and insurance. Use the actual tax rate for the districts you are shopping and a realistic insurance estimate — not a default that assumes somewhere else.
3. Stress-test the payment
Ask: if rates stay here, insurance goes up, or income dips for a quarter, are we still okay? If the answer is “barely,” the maximum is the wrong target.
4. Then look at price and program
Once the payment is right, we match it to a purchase price and the best structure — conventional, FHA, VA, jumbo, down payment assistance, or something else that fits your file.
5. Get preapproved for a range — shop to the comfortable number
Your preapproval can support options. Your offer strategy should aim at the home that fits the payment you chose on purpose.
Can I still stretch a little for the right house?
Sometimes, yes — thoughtfully.
Stretching for a home you will keep for a decade in a neighborhood you love can make sense if:
- You have reserves
- Your income is stable or rising
- You are not emptying every emergency fund to close
- You understand the payment with eyes open
Stretching because the approval letter said you could — without a plan for the rest of your life — is how buyers end up house-rich and cash-poor.
The goal is not the biggest house the guidelines allow.
The goal is the right house with a payment that still feels like freedom.
What about first-time buyers in Texas?
If you are buying for the first time, this gap between can and should shows up constantly.
You may qualify for more than you expected — especially with FHA, VA, conventional 3% down, or assistance programs. That is good news. It is also why we slow down and pick the payment first.
I would rather help you buy a home you can enjoy than help you buy the maximum and watch the payment crowd out everything else you care about.
The bottom line
How much house can I afford? is what underwriting calculates.
How much house should I buy? is what a mortgage strategy decides.
One is a ceiling.
The other is a plan.
If you want help finding your number — the comfortable one, not just the maximum — that conversation is free and there is no obligation. Bring your goals, your monthly realities, and the questions you have been turning over. We will build the payment and the path from there.
Buying Your First Home?
Download the First-Time Home Buyer’s Playbook and get a clear roadmap from preapproval to closing.