How Much Money Do I Really Need to Buy a House?
You may need far less than 20% down. Learn how down payment, closing costs, credits, gifts, deposits, and reserves affect how much cash you need to buy a home.
 Jason Herbert 10 min read
If you’re wondering how much money you really need to buy a house, here’s the first thing I want you to know:
You probably do not need 20% down.
Depending on the loan program and your qualifications, some conventional loans allow as little as 3% down, FHA financing can require as little as 3.5% down, and eligible VA and USDA buyers may be able to purchase with no down payment at all.
But there’s another side to this question that is just as important.
The down payment is not the same thing as the total amount of money you need to buy a house.
That distinction surprises a lot of first-time buyers.
When I help someone prepare to buy, I usually break the money needed into four different buckets:
- Your down payment
- Closing costs and prepaid expenses
- Upfront deposits and expenses during the transaction
- Money you want left over after closing
Once you look at it this way, figuring out whether you’re financially ready to buy becomes much easier.
Do I Really Need 20% Down to Buy a House?
No.
The idea that you need 20% down is probably one of the biggest misconceptions I still hear from potential home buyers.
Twenty percent can certainly be a good strategy in some situations. It may reduce your monthly payment, eliminate private mortgage insurance on many conventional loans, and lower the amount you have to finance.
But 20% down is not a requirement to buy a house.
Here are a few common examples:
| Loan Type | Potential Minimum Down Payment |
|---|---|
| Conventional | As little as 3% for certain qualified buyers |
| FHA | 3.5% |
| VA | Potentially 0% for eligible borrowers |
| USDA | Potentially 0% for eligible borrowers |
The important part is not automatically choosing the loan with the smallest down payment.
It is figuring out which financing strategy makes the most sense for your income, savings, monthly-payment comfort level, credit profile, and long-term plans.
Sometimes putting more money down is smart.
Sometimes keeping some of that money in the bank is smarter.
That is why I prefer to look at the entire financial picture instead of starting with, “How much can we get you approved for?”
How Much Would I Need on a $400,000 House?
Let’s make this real.
Suppose you are buying a $400,000 home.
Your down payment could look something like this:
| Down Payment | Cash for Down Payment |
|---|---|
| 3% | $12,000 |
| 3.5% | $14,000 |
| 5% | $20,000 |
| 10% | $40,000 |
| 20% | $80,000 |
That is a huge difference.
A buyer who thinks they need $80,000 before they can even consider a $400,000 home may actually have financing options with a dramatically smaller down payment.
But we still aren’t finished.
You also need to consider closing costs.
How Much Are Closing Costs When Buying a House?
Closing costs are separate from your down payment.
The Consumer Financial Protection Bureau recommends that buyers generally estimate approximately 2% to 5% of the purchase price for closing costs, although the actual amount depends on the property, loan, lender, location, and transaction.
On a $400,000 home, 2% to 5% would equal roughly:
$8,000 to $20,000.
Those costs can include items such as:
- Lender and loan-related fees
- Appraisal
- Title-related expenses
- Homeowners insurance
- Property-tax related amounts
- Prepaid interest
- Escrow deposits
- Other costs associated with the transaction
This is why simply taking the purchase price and multiplying it by your down-payment percentage doesn’t give you the whole answer.
For example, someone using 3% down on a $400,000 home might initially estimate:
$12,000 down payment + approximately $8,000–$20,000 in closing costs
That gives us an initial planning range of roughly $20,000–$32,000 before accounting for credits, assistance, deposits already paid, or other strategies.
And that last part is important.
Because the amount you ultimately have to bring to closing can sometimes be reduced significantly.
Can I Reduce the Amount of Cash I Need at Closing?
Absolutely.
This is where mortgage strategy becomes much more important than simply asking for an interest rate.
There are several ways we may be able to structure a transaction so that a buyer does not have to personally bring every dollar of the estimated costs.
Seller Credits
Depending on the loan program and transaction, the seller may be able to contribute toward allowable closing costs.
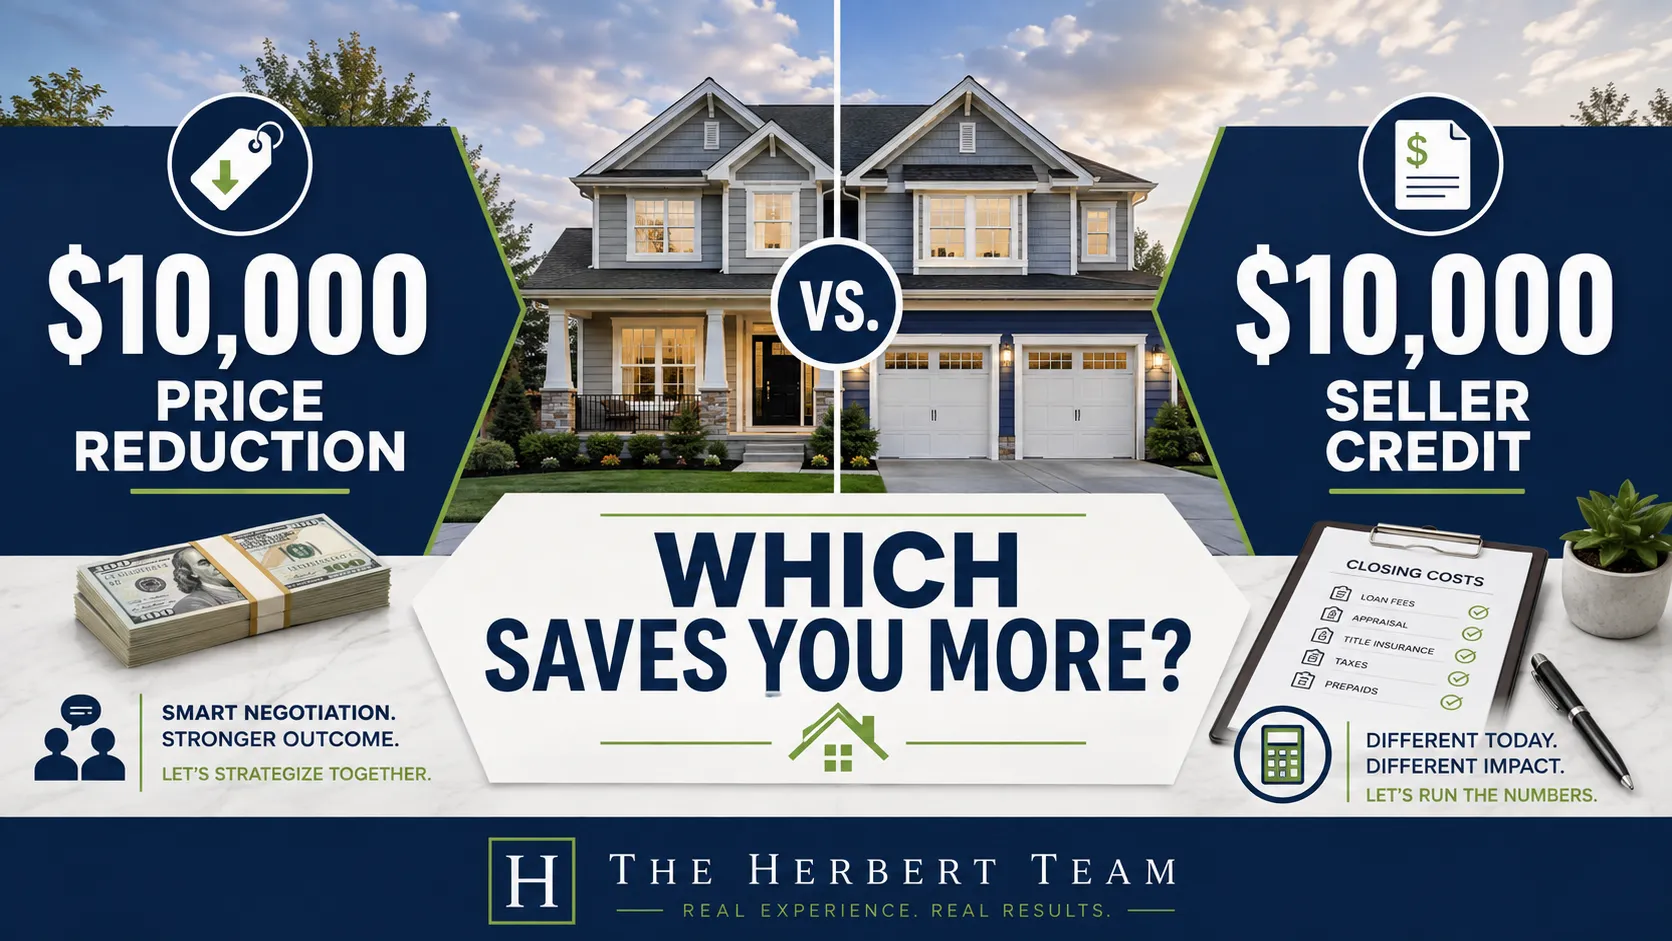
Instead of negotiating only on the sales price, there are situations where negotiating a seller credit can be more valuable to the buyer.
A $5,000 reduction in the price of a home doesn’t necessarily put $5,000 back into your checking account.
A properly structured $5,000 seller credit toward closing expenses might.
That can matter tremendously for a first-time buyer who has enough income to comfortably make the payment but doesn’t want to drain their savings account.
Lender Credits
Another potential option is using lender credits to offset certain closing costs.
There is usually a tradeoff involved — often through the interest-rate structure — so this is something that should be evaluated rather than automatically chosen.
The goal isn’t just to create the lowest cash-to-close number.
The goal is to find the best combination of cash needed today and monthly cost tomorrow.
Gift Funds
Qualified borrowers may also be able to use gift funds from eligible sources for some or all of their required funds.
So if parents or another eligible donor wants to help with the purchase, don’t assume that money can’t be used.
Talk with your lender before transferring funds so everything can be documented correctly.
Down Payment Assistance
There are also down-payment and closing-cost assistance programs available to certain buyers.
These programs vary based on location, income, occupation, loan program, and other eligibility requirements.
Some are grants.
Some are second liens.
Some are deferred.
Some have repayment requirements.
That means the right question is not simply:
“Is there down-payment assistance available?”
It is:
“Does the assistance actually improve my overall financing strategy?”
Those are two very different questions.
What About Earnest Money?
This is another place buyers sometimes get confused.
When your offer is accepted, you may need to provide earnest money and, depending on where you are buying, there may be other contract-related deposits or fees.
That doesn’t necessarily mean you need to add that entire amount again when estimating your final cash requirement.
Funds that are properly documented and credited through the transaction can reduce the amount still due from you at closing.
Think of it as money being paid earlier in the process, rather than automatically being an additional down payment.
You may also spend money before closing on items such as:
- Home inspection
- Additional property inspections
- Surveys in certain transactions
- Due-diligence related expenses
Those aren’t necessarily part of the number shown as “cash to close,” but they still need to be part of your home-buying budget.
Don’t Spend Every Dollar You Have on the House
This may be the most important section of the entire article.
Just because you can put every dollar you have into the transaction doesn’t mean you should.
Owning a house comes with expenses.
The air conditioner doesn’t care that you closed three weeks ago.
Neither does the water heater.
And moving into a new home almost always costs more than people expect.
There may be:
- Moving expenses
- Furniture
- Appliances
- Utility deposits
- Repairs
- Paint
- Landscaping
- Window coverings
- The inevitable trip — or five trips — to the hardware store
When I’m looking at different financing options with a buyer, I want to know what life looks like the day after closing, not just whether we can get the loan approved the day before closing.
There is a big difference between:
“I have $30,000 available and buying the house will use $29,500.”
and:
“I have $30,000 available and we structured the purchase so I still have $10,000–$15,000 available afterward.”
The second buyer usually has a lot more breathing room.
The best mortgage isn’t necessarily the one with the biggest down payment.
It’s the financing structure that fits the rest of your financial life.
Should I Put More Money Down If I Have It?
Maybe.
Putting more money down can provide several benefits:
- Smaller loan balance
- Lower monthly principal and interest payment
- Potentially lower mortgage-insurance costs
- More immediate equity
- Potentially better financing terms in some situations
But there is also a cost to putting more money down:
That money is now tied up in your house.
Let’s say you have $60,000 available.
The question isn’t simply whether you can put $60,000 down.
The better question might be:
Would I rather put $60,000 down, or put $35,000 down and keep $25,000 available for emergencies, investments, improvements, moving expenses, or other financial priorities?
There isn’t one correct answer.
That’s exactly why I like running multiple loan scenarios before someone makes the decision.
What If I Only Have $10,000 or $15,000 Saved?
Don’t automatically assume you can’t buy.
You also shouldn’t automatically assume that you can.
The answer depends on several things:
- Home price
- Income
- Credit
- Existing monthly debts
- Loan program
- Property location
- Seller contributions
- Gift funds
- Assistance programs
- How much money you want to retain after closing
This is where getting pre-approved before you’ve saved some arbitrary number can be incredibly helpful.
A good preapproval isn’t simply:
“Congratulations, you’re approved for $400,000.”
It should also answer questions like:
- What would my payment be?
- How much would I need for the down payment?
- What would my estimated cash to close look like?
- What happens if I put another $10,000 down?
- What happens if I put $10,000 less down?
- Could seller credits improve the structure?
- Are there assistance programs worth considering?
- How much money should I keep after the purchase?
Those are the numbers that actually help you make a decision.
So, How Much Money Should I Save Before Buying a House?
There isn’t one universal number.
But instead of thinking only about the down payment, start with this formula:
**Down Payment
- Closing Costs
- Upfront Purchase Expenses
- Desired Post-Closing Savings
− Available Credits, Gifts, or Assistance
= Your Real Home-Buying Cash Target**
That is a much better number to work toward.
You may discover you’re closer to buying than you thought.
Or you may decide that waiting a few months and building another $5,000 or $10,000 in savings would put you in a much stronger position.
Either answer is valuable.
The point of getting the numbers early is clarity.
Start With a Plan, Not a House Search
One of the easiest mistakes a first-time buyer can make is starting on Zillow or touring homes before knowing what the financing actually looks like.
I would reverse that.
First figure out:
What purchase price fits your monthly budget?
Then:
How much cash would you actually need?
Then:
Which loan structure gives you the best combination of payment, cash to close, and money left in the bank?
Once we know those three things, shopping for a house becomes a lot less stressful.
If you’re just beginning the process, I’ve also put together a First-Time Home Buyer’s Playbook that walks through the buying process from preparing your finances all the way through getting the keys.
Use it as a roadmap, and when you’re ready, we can put real numbers around your situation.
Frequently Asked Questions
Do I need 20% down to buy a house?
No. Certain qualified conventional buyers may be able to purchase with as little as 3% down, FHA financing can require as little as 3.5%, and eligible VA and USDA borrowers may have zero-down-payment options.
How much are closing costs when buying a home?
Closing costs commonly range from approximately 2% to 5% of the purchase price, although the actual amount depends on your loan, property, lender, location, and transaction.
Can a family member help with my down payment?
Often, yes. Many mortgage programs permit eligible gift funds, although documentation and donor requirements apply.
Can the seller pay my closing costs?
Seller contributions may be permitted depending on your loan program and transaction structure. The amount and eligible expenses vary, so this should be reviewed before writing the offer.
Can I buy a house with only $10,000 saved?
Possibly. It depends on the purchase price, loan program, available seller credits, gift funds, assistance programs, and the amount of savings you want to retain after closing. The best way to know is to have your lender build an actual purchase scenario rather than relying on a generic savings rule.
Is it better to make a bigger down payment?
Not always. A larger down payment can lower your loan balance and monthly payment, but it also reduces the amount of cash you keep available. The best down payment is the one that fits your overall financial plan, not automatically the largest amount you can afford.