Why Does My Mortgage Lender Ask About Bank Deposits?
Buying a home? Learn why a lender may ask about bank deposits, what records to prepare, and why mortgage program rules matter.
 Jason Herbert 3 min read
Your lender may ask about a deposit to verify that money needed for your home purchase comes from an acceptable source. A healthy account balance is useful, but the loan review also considers how those funds arrived.
If you are buying in Texas or California, send your loan officer a quick message before moving money for closing. A short conversation can help you prepare the right records.
What counts as a large deposit?
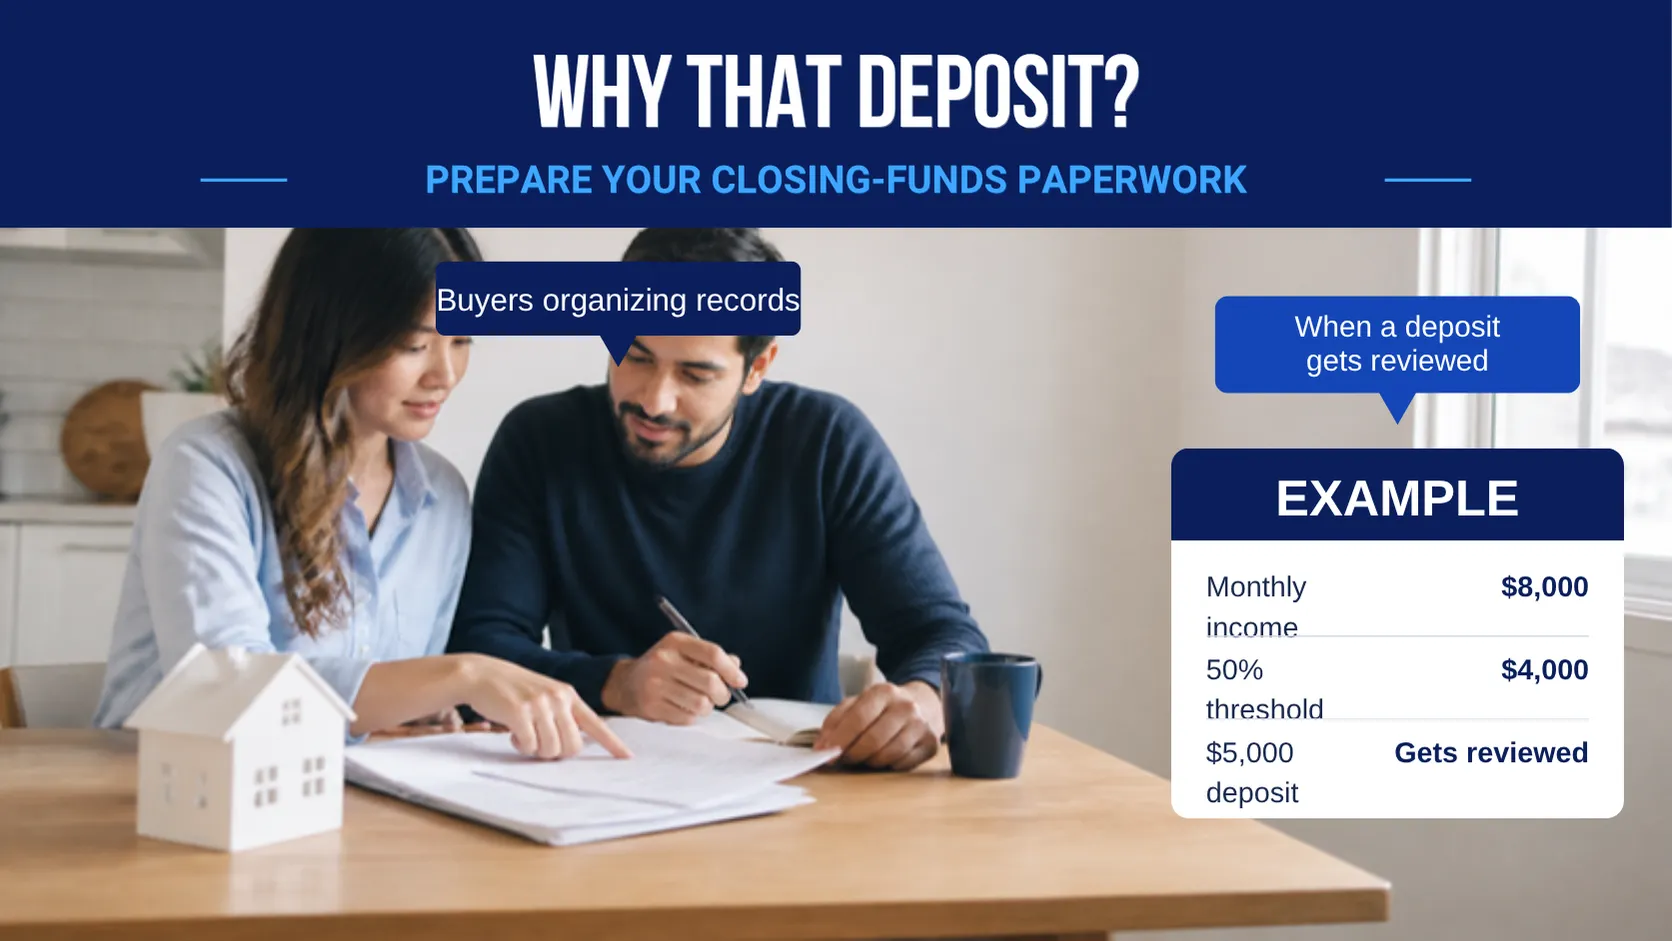
For a Fannie Mae conventional loan reviewed using bank statements (typically the most recent two months), a single deposit larger than 50% of the borrowers’ total monthly qualifying income meets its large-deposit definition. This is not a universal rule for every mortgage program.
Example: With $8,000 in monthly qualifying income, a $5,000 deposit exceeds the $4,000 threshold. That triggers review; it does not automatically mean denial.
See Fannie Mae’s depository-account guidance.
Does every deposit need a separate explanation?
Not necessarily. Under that guidance, a deposit whose source is clearly identified on the statement, such as payroll, Social Security, a tax refund, or a transfer between verified accounts, may need no additional explanation. If your lender uses Fannie Mae’s automated asset validation, the system itself flags which deposits, if any, need documentation. Questions about possible borrowed money can still require follow-up.
Ask your loan officer which specific transaction needs attention. Sending a pile of unrelated documents can make the conversation harder than it needs to be.
What should I prepare?
Start with a simple transaction list:
| Question | Information to gather |
|---|---|
| When did the money arrive? | Deposit date and amount |
| Where did it come from? | The actual source and purpose |
| Is repayment expected? | Whether it is a loan or another arrangement |
| Which records already exist? | Statements, transfer confirmations, or transaction records |
| When do you need the funds? | Your expected closing date |
This is a preparation checklist, not a promise that a particular document satisfies underwriting. Explain the real transaction and let your lender specify what is needed. Do not describe borrowed money as a gift.
Why is a balance screenshot sometimes insufficient?
Fannie Mae’s statement requirements include the financial institution’s name, the borrower as account holder, at least the last four digits of the account number, the period covered, all deposits and withdrawals, and the ending balance. A screenshot showing only a balance may omit needed information. Its guidance also permits other verification methods, including authorized third-party verification.
See Verification of Deposits and Assets.
Before sending financial records, ask for your lender’s approved secure upload method. Keep the original records available and avoid editing statement contents.
What if I cannot document the deposit?
For a Fannie Mae purchase, an undocumented large-deposit amount may have to be excluded from usable assets. The remaining verified funds must cover the required purchase funds and reserves.
Tell your lender early if a record is missing. Ask these questions:
- Which document or transaction remains unresolved?
- How much verified money is currently available for underwriting?
- Does the missing information affect our closing timeline?
- What acceptable documentation can I request from the original source?
The answer depends on the actual file. This article cannot determine whether your funds qualify.
Quick questions
Should I move money into one account before applying?
Ask first. Share your account list and proposed transfers with your loan officer so you know what records to retain.
Does a large deposit mean I cannot buy a home?
No automatic conclusion follows from the amount alone. Ask your lender to review the source and the full application.
Do FHA, VA, USDA, Freddie Mac, and jumbo loans follow this exact threshold?
Do not assume that. The threshold discussed here is Fannie Mae-specific. Your lender must identify the applicable program and requirements.
Plan your closing funds before you make an offer
You should feel comfortable asking why a document is needed. My goal is to help you understand the next step and keep your home purchase organized.
Buying in Texas or California? Contact me to discuss your financing and closing-funds plan. You can also request our First-Time Home Buyer’s Playbook.
Jason Herbert | The Herbert Team | NMLS #633039
TheHerbertTeam.com | 760-715-3434
Educational information only. Not a loan approval or legal or tax advice. Requirements vary by loan program, underwriting method, lender, and transaction. All loans are subject to review and approval.