Can I Keep the House After Divorce?
Review mortgage qualification, equity, affordability and possible financing paths before agreeing to keep the house after divorce.
 Jason Herbert 3 min read
When going through a divorce, one of the biggest questions is often:
“Can I keep the house?”
Sometimes the answer is yes.
But before agreeing to keep it, there’s another question that needs to be answered:
Can you realistically afford and finance the house on your own after the divorce?
Those are two different things.
Being Awarded the House Is Not the Same as Qualifying for the Mortgage
A divorce agreement may say that one spouse keeps the home.
But that doesn’t automatically mean the mortgage works for that person—or that the other spouse is automatically removed from the existing loan.
If both spouses are currently on the mortgage, there usually needs to be a separate plan for what happens to that loan.
That might involve refinancing, an eligible assumption, selling the property, or another approved solution depending on the mortgage and circumstances.
This is why I like having the mortgage conversation before the divorce agreement is final whenever possible.
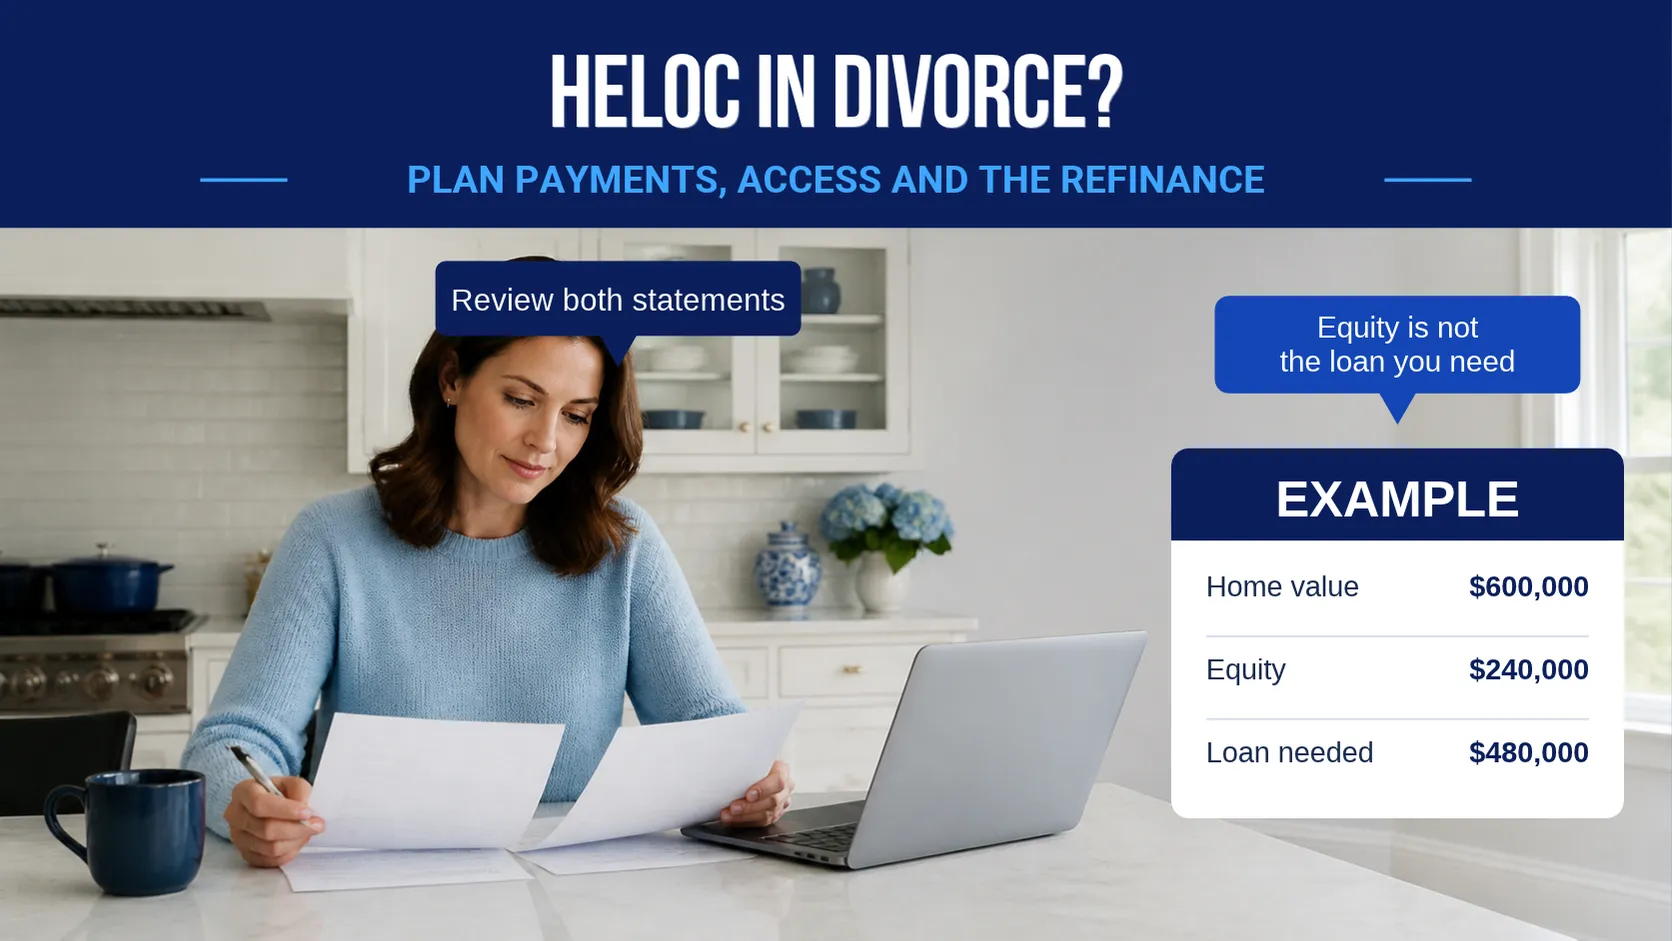
What About the Equity?
If one spouse keeps the home, the other spouse may also be entitled to an agreed share of the equity.
For example:
Home value: $600,000
Mortgage balance: $350,000
Approximate gross equity: $250,000
The attorneys determine how that equity is legally divided.
My job is to answer the next question:
If an equity buyout is required, can we actually finance it?
That needs to be figured out before someone agrees to a large buyout amount and assumes:
“We’ll just refinance later.”
Can You Afford the House After the Divorce?
This may be the most important part.
The household is changing from one financial unit into two.
The person keeping the home may now be responsible for the full:
- Mortgage payment
- Property taxes
- Homeowners insurance
- HOA dues
- Utilities
- Repairs and maintenance
So I don’t only want to know whether you can qualify for the mortgage.
I want to know whether the payment still makes sense for your life after the divorce.
The Best Time to Run the Numbers Is Before the Agreement Is Final
Before agreeing to keep the home, I like to answer three questions:
- What financing will be required?
- Can the spouse keeping the home qualify for it?
- Will the resulting payment be comfortable after the divorce?
That’s what I call a Mortgage Feasibility Review.
It doesn’t replace the advice of your divorce attorney.
It simply helps everyone understand whether the proposed housing plan is actually financeable.
Start With the Mortgage Plan
Keeping the house can absolutely be the right decision.
But I don’t want someone finding out after the divorce is finalized that the refinance, equity buyout, or monthly payment doesn’t work the way everyone expected.
If the marital home is part of your divorce discussions, getting the mortgage numbers early can help you and your attorney make better-informed decisions.
I’ve also created The Herbert Team’s Divorce and the Mortgage Guide to help homeowners understand the mortgage questions that can come up before, during, and after divorce.
Use it as a starting point, and when you’re ready, we can review your specific situation.
Frequently Asked Questions
Can I keep my house after divorce?
Potentially. It depends on the property division, existing mortgage, required equity buyout, and whether the spouse keeping the home can qualify for and afford the necessary financing.
Does a divorce decree automatically remove my ex from the mortgage?
Not necessarily. Ownership of the property and responsibility to the mortgage lender are separate issues.
Should I talk to a lender before the divorce is final?
If the home or mortgage is part of the divorce, reviewing the financing before finalizing the agreement can help identify potential issues early.
This article is for mortgage-planning and educational purposes only and is not legal or tax advice. Divorce and property-division questions should be reviewed with qualified legal professionals.