Preapproved for a Mortgage? Avoid These 9 Mistakes Before Closing
Already preapproved for a mortgage? Avoid these nine mistakes involving credit, employment, bank accounts, purchases, and closing funds before you get the keys.
 Jason Herbert 10 min read
You’ve been preapproved.
Your offer was accepted.
The appraisal and inspection are moving forward.
Now you can relax and start buying furniture for the new house, right?
Not quite yet.
One of the biggest misunderstandings in the mortgage process is that a preapproval permanently locks in your qualification.
It doesn’t.
Your preapproval is based on a financial snapshot that includes your:
- Income
- Employment
- Credit
- Monthly debts
- Available funds
- Down payment
- Financial reserves
- Proposed property and loan structure
If something important changes before closing, the lender may need to evaluate the loan again.
That doesn’t mean you should put your life completely on hold.
It means you should talk to your loan officer before making a financial move that could change the information used to approve your mortgage.
Here are nine mistakes I want buyers to avoid between preapproval and closing.
1. Opening a New Credit Account
The first rule is simple:
Do not open new credit without talking to your loan officer.
That includes:
- Credit cards
- Auto loans
- Furniture financing
- Appliance financing
- Personal loans
- Buy-now-pay-later accounts
- New lines of credit
The offer may sound harmless:
“No payments for twelve months.”
But the lender may still need to account for the new debt, new balance, credit inquiry, or required future payment.
Current Fannie Mae guidance on liabilities states that when an additional liability is disclosed or discovered through closing, the lender may need to recalculate the borrower’s debt-to-income ratio.
A new monthly payment can reduce the mortgage amount you qualify for or require the loan to be resubmitted through underwriting.
Wait until the home has closed before applying for the furniture-store card.
2. Making a Large Purchase on an Existing Credit Card
You may not need to open a new account to create a problem.
Putting thousands of dollars of furniture, electronics, travel, or moving expenses on an existing credit card can increase:
- The outstanding balance
- The minimum required payment
- Credit utilization
- The borrower’s debt-to-income ratio
Imagine that your credit card had a $50 minimum payment when you were preapproved.
You then charge $8,000 for new furniture.
If the updated required payment is significantly higher, the lender may need to use the new payment when evaluating the loan.
That does not mean every routine purchase creates a mortgage emergency.
But if the purchase is large enough to affect your balances, monthly obligations, credit, or remaining funds, talk to your loan officer first.
3. Buying or Leasing a Car
A vehicle purchase is one of the fastest ways to change a mortgage approval.
Even if the dealership says:
“Your payment is only $650 per month.”
That is still another $650 monthly obligation that may need to be included in your qualification.
Suppose your mortgage approval was already close to the allowable debt-to-income limit.
A new car payment could:
- Reduce your approved purchase price
- Require other debts to be paid off
- Change the loan program
- Delay underwriting
- Make the current transaction no longer qualify
This applies to both buying and leasing.
If your car suddenly needs to be replaced while you are under contract, call your loan officer before signing anything.
We can run the proposed payment through the mortgage numbers and tell you what it may change.
4. Changing Jobs, Pay Structure, or Employment Status
Not every job change will prevent a mortgage closing.
A better job with higher pay may be perfectly workable.
But the lender still needs to evaluate and document the change.
A job move can become more complicated when it involves:
- Switching from W-2 employment to self-employment
- Changing from salary to commission
- Moving from guaranteed hours to variable hours
- Starting contract or 1099 work
- Taking an unpaid leave
- Reducing hours
- Changing industries
- Creating a gap before the new job begins
- Quitting before closing
Lenders may also reverify employment near closing. Fannie Mae maintains specific verification-of-employment requirements for loans using employment income.
Do not assume a raise automatically means the job change is irrelevant to underwriting.
Call before accepting, resigning, changing your hours, or changing how you are paid.
5. Moving Money Without Preserving the Paper Trail
Moving your own money from savings to checking is not inherently a problem.
The issue is documentation.
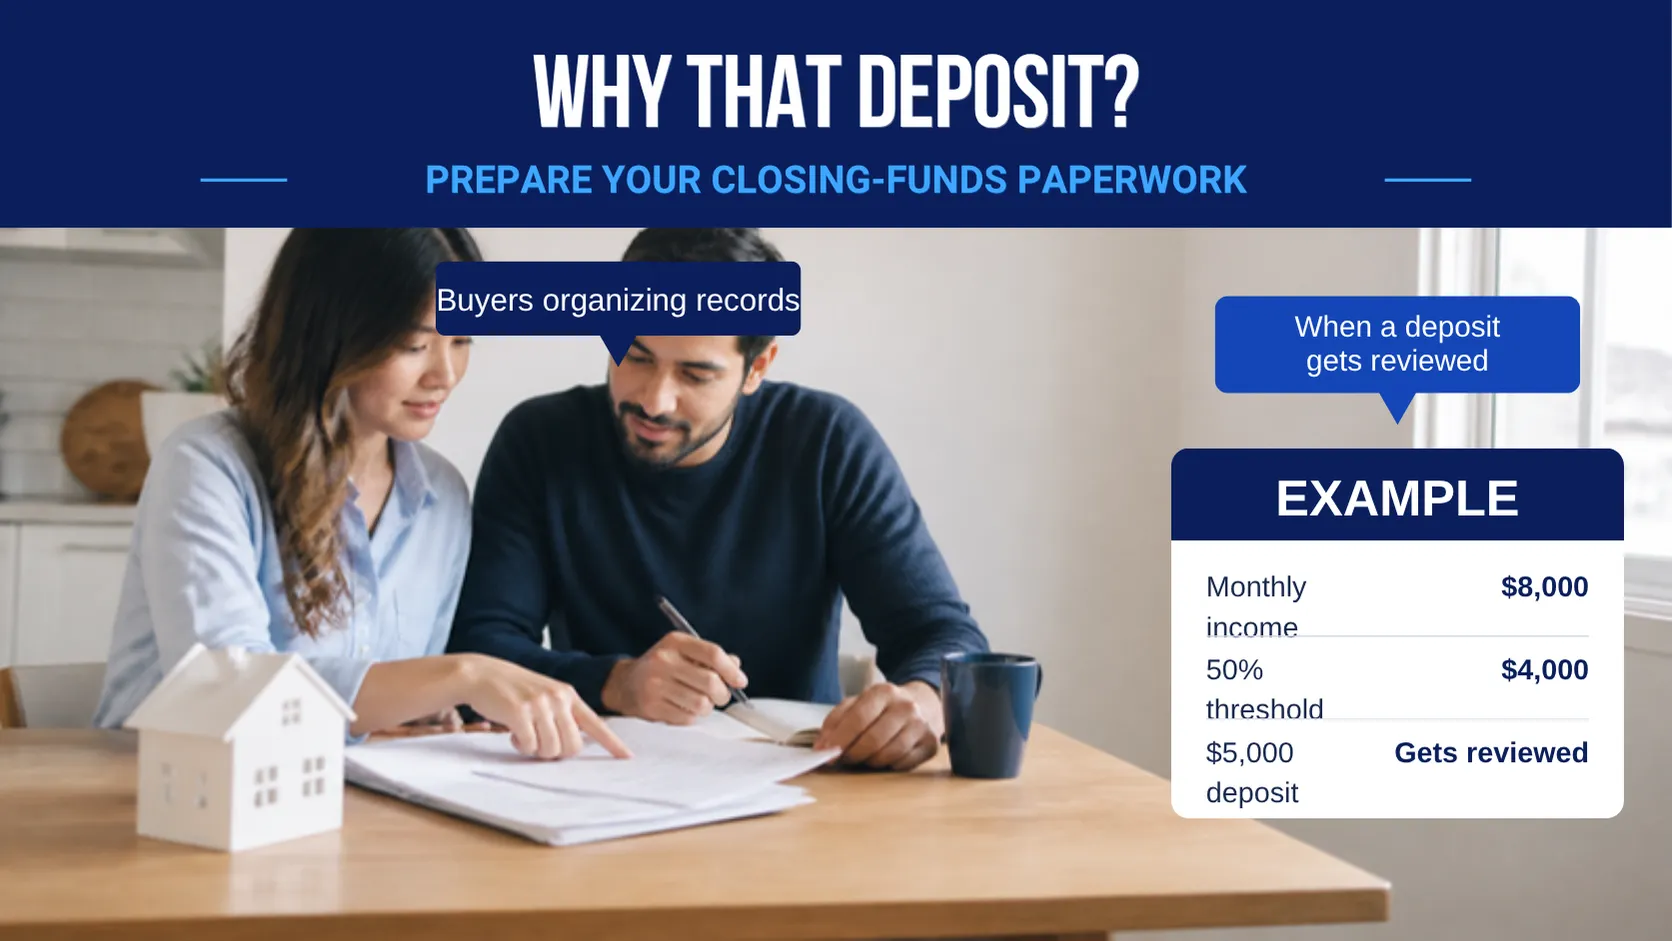
If the lender sees a large deposit or transfer, we may need to show where the funds came from.
For purchase transactions, current Fannie Mae depository-account guidance generally requires lenders to evaluate large deposits. When those funds are needed for the down payment, closing costs, or reserves, the source may need to be documented.
Common examples include:
- Transferring funds between banks
- Cashing out an investment account
- Selling a vehicle
- Receiving gift funds
- Depositing a bonus
- Moving money from a business account
- Receiving proceeds from another property
- Depositing cash kept at home
Keep complete statements and transfer confirmations for both sides of the transaction.
If you sell an asset, keep the sales agreement, proof that you owned the asset, proof of payment, and deposit record.
The money may be acceptable.
We simply need to be able to document it correctly.
6. Depositing Undocumented Cash
A large cash deposit can be especially difficult to verify.
You may know exactly where the money came from.
But mortgage underwriting is based on documentation—not just an explanation.
For example:
“I’ve been saving this cash at home for years.”
That may be completely truthful, but traditional mortgage guidelines may not allow us to use the funds if we cannot establish an acceptable source and paper trail.
Before depositing cash that you expect to use toward the transaction, talk to your loan officer.
Never borrow money temporarily, deposit it, and present it as your own savings.
Be transparent about where every significant source of closing funds came from.
7. Spending the Money Reserved for Closing
Not every problematic purchase involves credit.
A large cash purchase can also affect the mortgage if it reduces the funds available for:
- Down payment
- Closing costs
- Prepaid taxes and insurance
- Required reserves
- Debt payoffs
- Moving expenses
- Post-closing savings
Suppose your approval requires $35,000 to close and an additional $10,000 in verified reserves.
You then spend $12,000 from the same account on furniture and moving expenses.
Even without creating new debt, the account may no longer contain enough verified funds to satisfy the loan requirements.
The amount shown on the original estimate may also change as taxes, insurance, credits, and prorations are finalized.
Keep a cushion and avoid treating every dollar above the first estimated cash-to-close figure as available spending money.
8. Missing a Payment or Co-Signing for Someone Else
Continue paying every bill on time.
That includes:
- Mortgages
- Rent
- Credit cards
- Auto loans
- Student loans
- Personal loans
- Court-ordered obligations
Moving, packing, travel, and closing preparations can make it surprisingly easy to overlook a payment.
Set reminders or automatic payments where appropriate, but continue monitoring the accounts.
Also, do not co-sign for another person while your mortgage is in process.
When you co-sign, you may become legally responsible for that debt. The payment may need to be considered even if the other person promises to make it.
Helping someone buy a car three days before your own mortgage closing is terrible timing.
9. Paying Off or Closing Accounts Without a Mortgage Plan
This one surprises people.
Paying off debt can be helpful.
But you should not change the approved debt strategy without coordinating with your loan officer.
The mortgage approval may already specify:
- Which account must be paid
- The required payoff amount
- Whether it will be paid before or at closing
- Which funds will be used
- What documentation is needed
- Whether the account should remain open
Fannie Mae has specific requirements for debts paid before or at closing.
Paying a debt from the wrong account could reduce required closing funds or reserves.
Closing a revolving account may also change the credit profile.
Before paying off, paying down, transferring, or closing an account, confirm the mortgage plan.
What Should You Do If Something Has Already Changed?
Call your loan officer.
Do not hide the change and hope it will not be discovered.
Most issues are easier to solve when we know about them early.
Tell us immediately if:
- You changed jobs
- Your hours or pay changed
- You opened new credit
- You financed a purchase
- Your credit balance increased substantially
- You received or transferred a large sum
- A gift donor changed
- Your closing funds decreased
- You co-signed for someone
- A debt or collection appeared
- You are separating, divorcing, or changing how title will be held
- You expect any other meaningful financial change
We can determine whether updated documents are needed and whether the loan still works as structured.
The worst strategy is waiting until the day before closing.
Review the Closing Disclosure Carefully
For most mortgages, the lender must provide a Closing Disclosure at least three business days before closing.
The Consumer Financial Protection Bureau recommends using that time to confirm the loan details and resolve unexpected differences.
Review:
- Loan amount
- Interest rate
- Loan type and term
- Monthly principal and interest
- Mortgage insurance
- Property taxes and homeowners insurance
- Closing costs
- Seller and lender credits
- Cash to close
- Prepayment-penalty information
- Names and property address
Compare the Closing Disclosure with your most recent Loan Estimate.
If something does not look right, ask before you sign.
Protect Your Closing Funds From Wire Fraud
Closing is also when buyers can become targets of wire fraud.
Scammers may impersonate a real estate agent, lender, title company, attorney, or escrow officer and send fake last-minute wire instructions.
The Federal Trade Commission warns buyers not to wire closing funds in response to an unexpected email changing the destination account.
Before sending money:
- Use a known, independently verified phone number.
- Call the title or settlement company directly.
- Confirm the wiring instructions verbally.
- Verify the account and routing numbers.
- Be suspicious of any unexpected last-minute change.
Do not rely on the phone number contained in the suspicious message itself.
If you believe funds were sent to a fraudulent account, contact your bank or wire-transfer provider immediately.
The Simple Rule Until You Get the Keys
Between preapproval and closing, keep your finances as stable and well documented as possible.
Before making a financial change, ask:
Could this affect my income, credit, monthly debts, cash to close, or financial reserves?
If the answer might be yes, call your loan officer first.
I would much rather review a proposed decision before you make it than try to repair the mortgage approval afterward.
The Herbert Team’s First-Time Home Buyer’s Playbook explains the full process—from preparing and getting preapproved through underwriting, appraisal, closing, and getting the keys.
Understanding what happens after preapproval can be just as important as getting preapproved in the first place.
Frequently Asked Questions
Can I use my credit card after being preapproved for a mortgage?
Yes, normal responsible use may be fine. Avoid large purchases or balance increases that could affect your credit, minimum payments, debt-to-income ratio, or available funds. Ask your loan officer before making a significant purchase.
Can I buy furniture before closing?
It is safest to wait until the mortgage has closed. Financing furniture, opening a store card, increasing credit-card balances, or spending required closing funds can affect the approval.
Can I change jobs before closing on a house?
Potentially, but the lender must evaluate and document the change. A move involving self-employment, commission income, reduced hours, contract work, or an employment gap can be particularly important. Speak with your loan officer before making the change.
Can I move money between my bank accounts before closing?
Yes, but preserve the complete paper trail. The lender may need statements or transfer records showing the funds leaving one verified account and entering the other.
Can I deposit cash before closing?
A cash deposit may be difficult to document as an acceptable source of mortgage funds. Speak with your lender before depositing cash you expect to use for the transaction.
Should I pay off credit cards before closing?
Only according to the mortgage plan established with your loan officer. Paying off debt can help, but using the wrong funds or changing accounts without coordination can create new documentation or reserve issues.
Will the lender check my employment again before closing?
Employment may be reverified near closing when employment income is being used to qualify. Tell your lender immediately about changes to your employer, position, pay structure, hours, leave status, or expected start date.
When will I receive my final closing numbers?
For most mortgages, the Closing Disclosure must be provided at least three business days before closing. Review it against your latest Loan Estimate and ask about unexpected changes.
How can I avoid a mortgage wire scam?
Never act on unexpected emailed instructions changing where your closing funds should be sent. Call the title or settlement company using a trusted phone number and verify all instructions before wiring money.
This article provides general mortgage-education information and is not financial, legal, tax, or credit-repair advice. Loan requirements vary by loan program, borrower, lender, property, and individual circumstances. Always discuss financial or employment changes with your loan officer before acting.