What Is an Owelty Lien in a Texas Divorce—and Can It Help One Spouse Keep the House?
Learn how a Texas owelty lien may help structure a divorce equity buyout when one spouse keeps the home, including appraisal, refinancing, qualification, and timing.
 Jason Herbert 10 min read
When one spouse wants to keep the marital home after a Texas divorce, one of the biggest questions is often:
“How do I pay my spouse their share of the equity without selling the house?”
One possible solution is a Texas owelty lien.
It can be a valuable mortgage-planning tool when it is established correctly and the spouse keeping the home can qualify for the resulting mortgage.
But an owelty is not simply another name for a cash-out refinance.
It is a legal lien connected to the division of jointly owned property.
That means the divorce attorney, title company and mortgage professional each have a different role in getting the structure right.
What Is an Owelty Lien?
In simple terms, an owelty can be used when one person receives the property and owes the other person money to equalize the division ordered under Texas Family Code Section 7.001.
The Texas Constitution, Article XVI, Section 50(a)(3) recognizes an owelty of partition imposed against the property by court order or written agreement. It specifically includes a debt from one spouse to the other resulting from the division or award of a family homestead in a divorce.
Here is the basic concept:
- One spouse is awarded the home.
- The other spouse is awarded a defined equity interest.
- An owelty lien secures the amount owed to the departing spouse.
- A properly structured refinance may then pay the existing mortgage and the owelty lien.
- The spouse keeping the home becomes responsible for the new mortgage, subject to qualification and closing requirements.
The legal documents create the obligation and lien.
The mortgage determines whether the spouse keeping the home can actually finance the proposed result.
A Simple Equity-Buyout Example
Assume Jason and Sarah own a Texas home together.
For illustration:
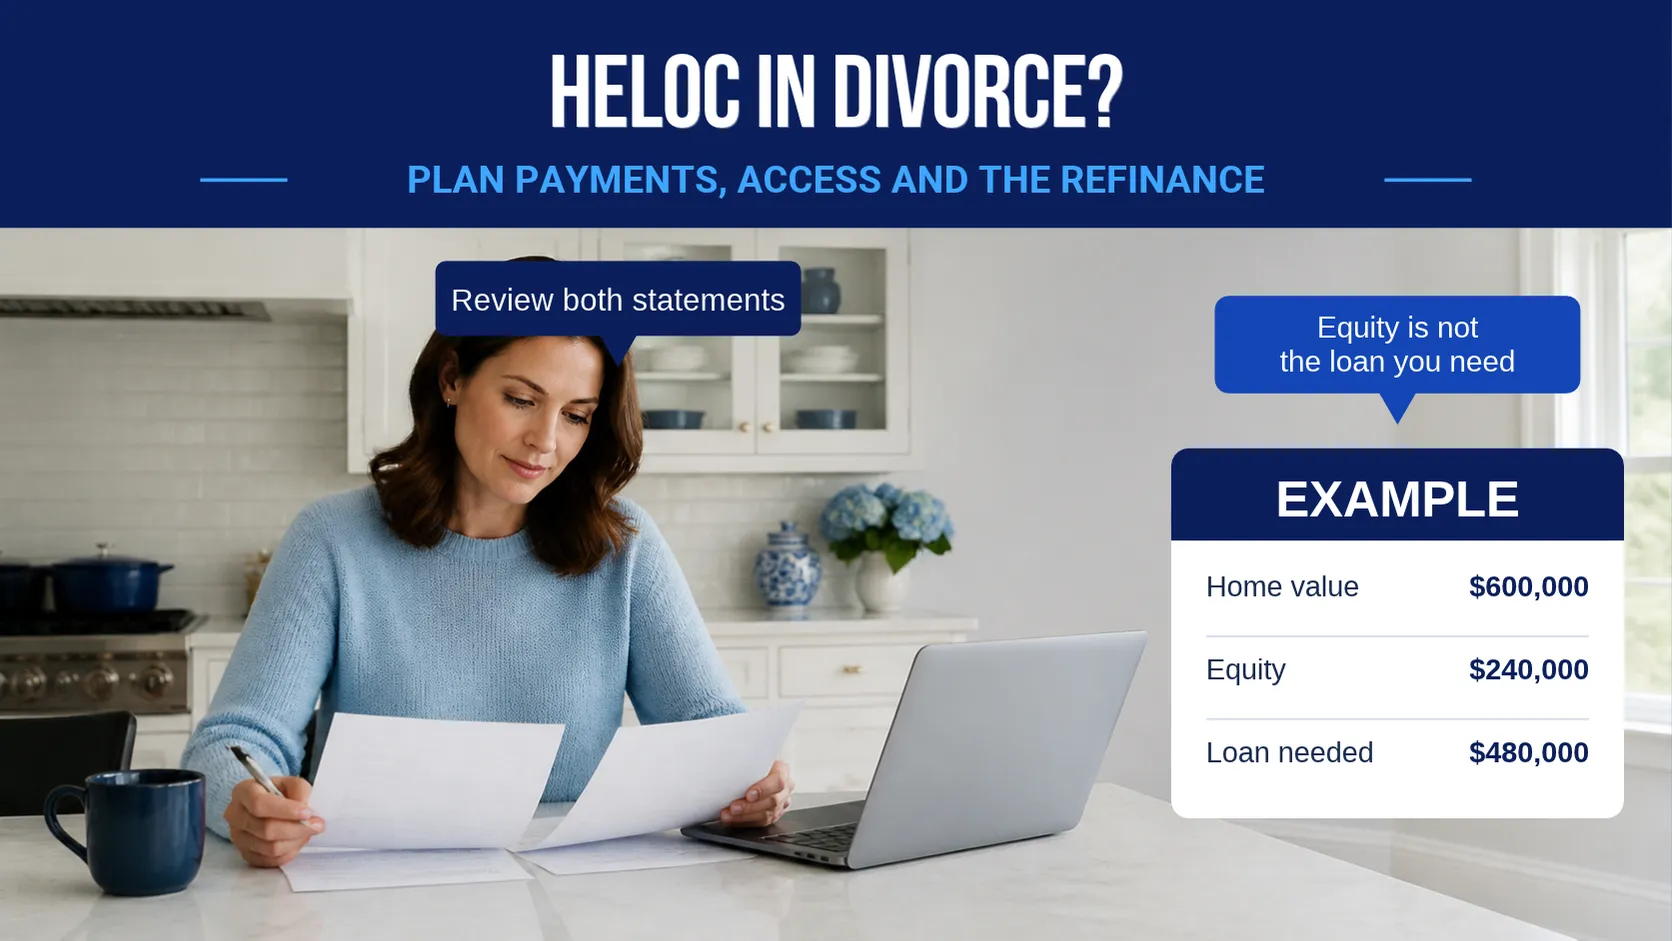
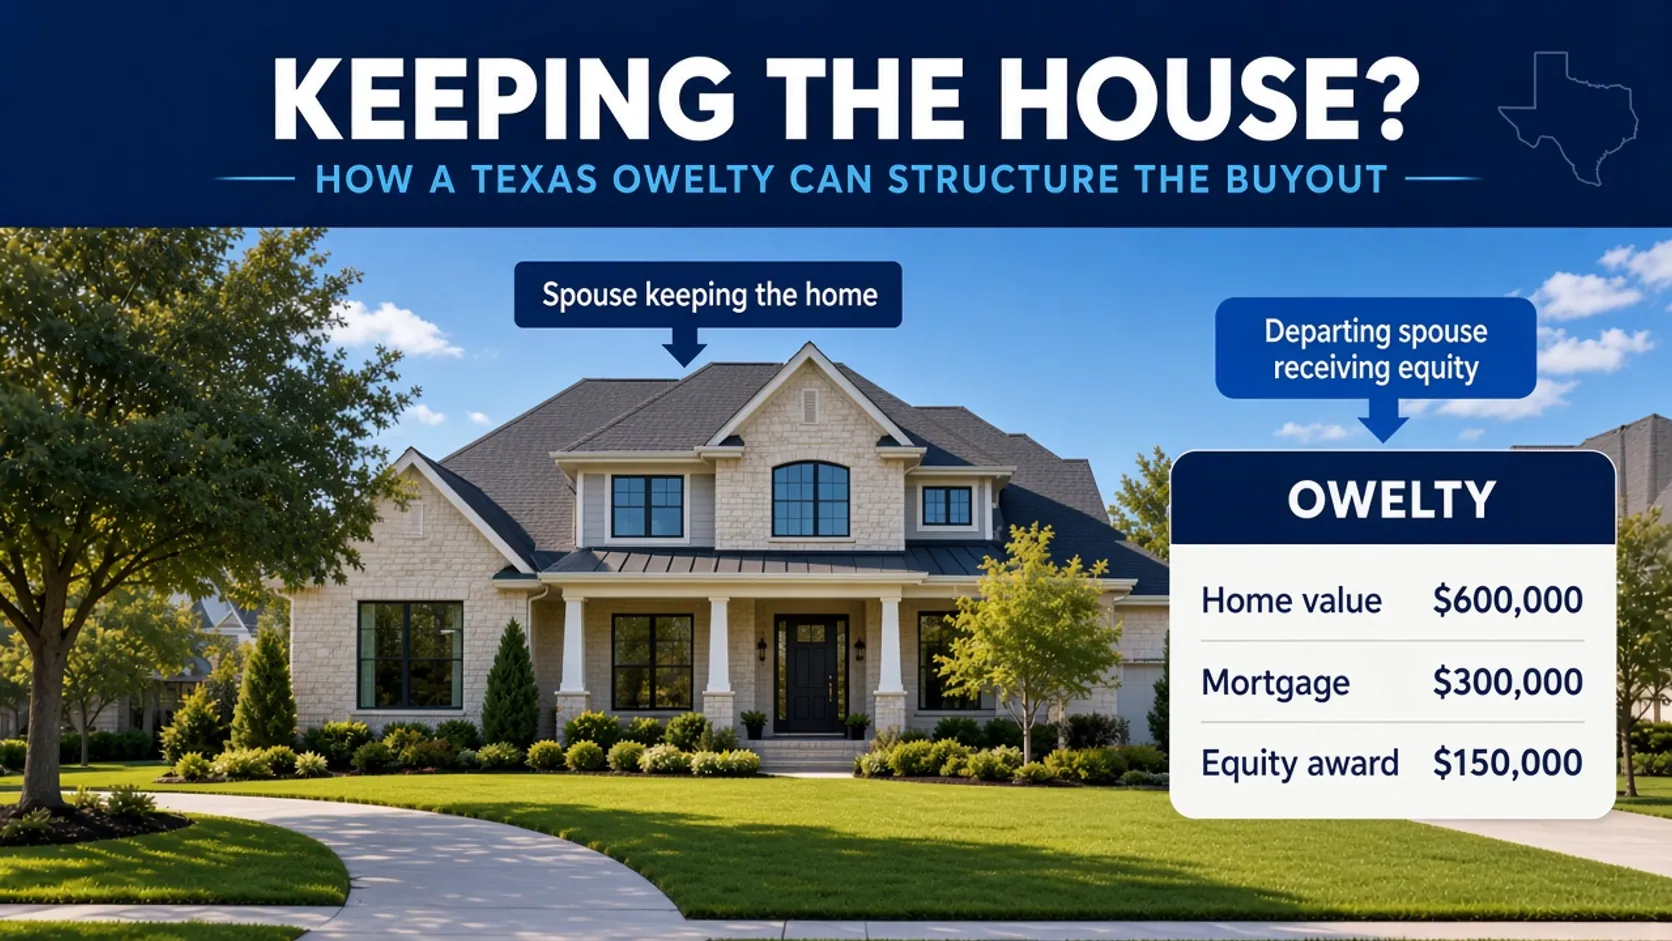
- Appraised value: $600,000
- Existing mortgage: $300,000
- Estimated gross equity: $300,000
- Proposed equity award to the departing spouse: $150,000
If Sarah is keeping the home, she may need enough financing to:
- Pay off the existing $300,000 mortgage
- Pay the $150,000 equity obligation to Jason
- Cover eligible closing costs and prepaid items
Conceptually, that could place the new loan near $450,000 before considering closing costs, credits, adjustments, other liens or program limitations.
But that is only a simplified illustration.
The actual calculation may be affected by:
- The value used by the parties
- The current mortgage payoff
- Other liens
- Agreed credits or reimbursements
- Selling-cost adjustments, if included in the settlement
- The exact equity percentage or dollar amount awarded
- Closing costs and prepaid items
- Maximum loan-to-value requirements
- The mortgage program
- The borrower’s qualification
This is why I prefer a clear calculation method in the divorce agreement instead of relying on a vague statement such as:
“The parties will divide the equity equally.”
The attorneys determine the appropriate legal language.
From the mortgage side, I need to be able to identify the amount that must be financed and paid at closing.
Why Not Just Use a Regular Cash-Out Refinance?
A common question is:
“Why can’t the spouse keeping the home simply take cash out and write the former spouse a check?”
Sometimes a cash-out refinance may be an available solution.
But Texas homestead rules, divorce documentation and mortgage-program requirements can make the correct structure extremely important.
An owelty establishes a secured property-division obligation rather than treating the payment as an informal withdrawal of equity.
That does not mean every owelty transaction automatically receives rate-and-term treatment, higher loan-to-value limits, lower pricing or easier approval.
The refinance classification depends on:
- The applicable loan program
- The legal agreement
- The lien and title documentation
- Who receives the proceeds
- Whether the borrower receives cash back
- Existing liens
- Ownership history
- Lender requirements
For example, current Fannie Mae cash-out refinance guidance includes specific provisions for buying out a co-owner pursuant to a legal agreement and exceptions when property is legally awarded through divorce.
Other conventional, FHA, VA and portfolio programs may treat the transaction differently.
The word owelty by itself does not determine the mortgage classification.
The complete structure does.
The Spouse Keeping the House Still Has to Qualify
An owelty does not create mortgage qualification.
Sarah still needs to qualify for the proposed new loan.
The review may include:
- Employment and qualifying income
- Credit
- Monthly debts
- Child support or spousal-maintenance obligations
- Support income being used to qualify
- Property taxes
- Homeowners insurance
- Homeowners association dues
- The proposed loan amount
- The resulting monthly payment
- Available assets and reserves
- The appraisal
- Applicable loan-program requirements
This is where mortgage feasibility becomes critical.
A proposed decree may require Sarah to refinance and pay Jason $150,000 within 60 or 90 days.
But can Sarah qualify for the necessary loan?
If the answer is no, the legal deadline does not cause the mortgage guidelines to change.
That question should be evaluated before the agreement depends on a refinance that may not be possible.
The Appraisal Can Change the Plan
An equity buyout is often based on the home’s value.
But whose value?
A real estate agent’s market analysis can help with planning.
An online estimate may provide a rough starting point.
The parties may also agree on a third-party appraisal for settlement purposes.
The mortgage lender will still need to follow the appraisal or valuation requirements of the selected loan program.
Suppose the proposed settlement uses a value of $650,000, but the lender’s appraisal supports $600,000.
That difference can affect:
- Available equity
- The maximum permitted loan amount
- The equity-buyout calculation
- The required loan-to-value
- Whether the proposed refinance works
When possible, the divorce agreement should address how the value and equity calculation will be determined if the final mortgage valuation differs from an earlier estimate.
That is a legal drafting question for the attorneys.
My role is to model the financing consequences.
The Existing Mortgage Does Not Disappear
The owelty handles the property-division debt.
It does not automatically remove either spouse from the existing mortgage.
If both spouses signed the current mortgage, both may remain contractually liable until the lender releases one of them, the mortgage is paid off, or another approved solution is completed.
A new refinance can potentially:
- Pay off the existing mortgage
- Pay the documented owelty lien
- Place the new financing in the retaining spouse’s name
- Complete the equity payment through closing
But the transaction must close successfully before the old mortgage is paid off.
Do not assume the departing spouse is protected merely because the decree says the other spouse will make the payments.
What Happens to the Departing Spouse?
The departing spouse usually wants two separate outcomes:
- Receipt of the agreed equity
- Release from responsibility for the existing mortgage
Those are related, but they are not the same.
The owelty secures the equity obligation.
Paying off or otherwise resolving the existing mortgage addresses the mortgage liability.
Until the mortgage issue is completed, missed payments can still affect a borrower whose name remains on the debt.
The departing spouse may also want to purchase another home.
Current Fannie Mae guidance on property-settlement buyouts addresses how an existing mortgage may be evaluated when one co-owner’s property interest has been bought out. Documentation and loan-program requirements matter, and a title transfer does not itself contractually release someone from the old mortgage.
Both spouses therefore need to understand the actual sequence:
- Divorce agreement
- Property and lien documents
- Mortgage approval
- Refinance closing
- Equity payment
- Existing mortgage payoff
- Final title and lien recording
When Should the Mortgage Review Begin?
Ideally, the review begins before the divorce agreement is finalized.
That gives us time to evaluate:
- The proposed property value
- The mortgage payoff
- The proposed equity award
- The new loan amount
- The retaining spouse’s qualification
- Estimated payment
- Loan-to-value limits
- Program options
- Support obligations or income
- The expected legal and mortgage timeline
A preliminary feasibility review is not a guarantee that the future loan will close.
Income, assets, credit, interest rates, property value and program requirements can change.
But it is far better than creating a housing obligation without first testing the numbers.
Why the Legal and Mortgage Documents Must Work Together
An owelty is a legal structure.
The mortgage professional should not draft it.
The divorce attorney and title professionals should determine the documents needed to properly create, secure and record the obligation.
The lender then reviews the completed legal and title documentation under the selected mortgage program.
Problems can arise when:
- The decree uses vague equity language
- The equity amount cannot be determined
- The lien was not properly created or documented
- The property description is incomplete
- The proposed proceeds do not match the legal obligation
- The retaining spouse expects unrestricted cash back
- Title and mortgage timelines do not align
- The refinance deadline is too short
- The spouse keeping the home cannot qualify
Early coordination can help identify these problems while the parties may still have options.
A Note for Texas Divorce Attorneys and Mediators
If one spouse is expected to retain the homestead and pay the other spouse for their equity, useful mortgage questions include:
- What value will be used?
- Will the equity be expressed as a percentage, dollar amount, or formula?
- What mortgage payoff will be deducted?
- Will any other liens, credits or reimbursements affect the calculation?
- How and when will the equity amount become fixed?
- Will an owelty lien be used?
- Can the retaining spouse qualify for the estimated new loan?
- What happens if the appraisal is lower than expected?
- Is the proposed refinance deadline realistic?
- What happens if financing is unavailable?
- When will the departing spouse receive payment?
- How will the existing joint mortgage be resolved?
These are not recommendations about how the marital estate should be divided.
They are questions that help determine whether the proposed housing plan is financeable.
I can provide a Mortgage Feasibility Review for the client and, with the client’s permission, coordinate with the attorney regarding the mortgage consequences.
An Owelty Can Be Powerful—But It Must Be Planned
A Texas owelty lien may help create a clear path for one spouse to keep the marital home while paying the other spouse an awarded share of the equity.
But it does not replace:
- A properly prepared divorce agreement
- Appropriate lien and title documentation
- A reliable property value
- Mortgage qualification
- A realistic closing timeline
- Coordination among the client, attorney, title company and lender
The earlier the mortgage analysis begins, the easier it is to determine whether keeping the house is financially realistic.
The Herbert Team’s Divorce and the Mortgage Guide explains additional mortgage issues that can arise before, during and after divorce.
You can also visit our Divorce Mortgage Planning page to request a confidential Mortgage Feasibility Review.
Frequently Asked Questions
What is an owelty lien in a Texas divorce?
An owelty lien can secure a debt owed by one spouse to the other when the marital home is awarded to one spouse and an equity payment is required to equalize the property division.
Does an owelty automatically remove my former spouse from the mortgage?
No. The owelty addresses the equity obligation. Removing a borrower from the existing mortgage generally requires a lender-approved release, payoff, refinance or other accepted solution.
Does the spouse keeping the house have to qualify for the refinance?
Yes. The borrower must satisfy the applicable lender and loan-program requirements for income, credit, debts, assets, property value and the proposed mortgage payment.
Is an owelty refinance always treated as a rate-and-term refinance?
No. Classification depends on the mortgage program, legal agreement, lien documentation, proceeds, ownership history and lender requirements. The presence of an owelty lien alone does not determine the classification.
Can the spouse keeping the home receive extra cash?
Do not assume unrestricted cash back will be available. An equity-buyout structure is generally designed to pay documented liens and obligations through closing. Any borrower cash back is subject to the selected program and transaction classification.
How is the equity amount calculated?
The divorce agreement may use a dollar amount, percentage or formula. The calculation may consider the agreed property value, mortgage payoff, other liens, credits, reimbursements and other settlement terms. The attorneys determine the legal division.
What if the lender’s appraisal is lower than the value used in the divorce agreement?
A lower appraisal may reduce the available financing and prevent the proposed mortgage from paying the full equity obligation. The agreement should be reviewed by the attorneys for how that possibility will be handled.
When should we complete a Mortgage Feasibility Review?
Ideally, before the divorce agreement creates a refinance deadline or relies on a specific equity payment. Early review provides time to test the value, loan amount, payment and borrower qualification.
This article provides general mortgage-planning information and is not legal, tax, title, financial-planning, or credit advice. An owelty is a legal lien structure that should be prepared and reviewed by qualified Texas legal and title professionals. Mortgage requirements vary by loan program, lender, borrower, property, documentation, and individual circumstances.